 Pearl
 Quantus
 Pudgy Penguins
 Aerodrome Finance
 Quack AI
 Zcash
 NEAR Protocol
PayPal stock faced renewed pressure on Oct. 26 as investors prepared for third-quarter earnings. Shares approached $55 during Monday’s session after closing at $57.02 on Friday.
The results, scheduled for Oct. 27, will test expectations for PayPal’s business recovery. Slowing account growth, competition, and declining PYUSD supply remain important concerns.
PayPal Stock Rises Ahead of Q3 Earnings
PYPL stock will be in the spotlight this week as the company releases its earnings. Based on the last earnings report, analysts are not upbeat about this report.
Yahoo Finance data shows that analysts expect that its quarterly revenue will be $8.71 billion, up by 3.43% from a year earlier. This revenue growth is much lower than what the company used to have a few years ago, when it was one of the fastest-growing companies in the US.
The most recent results showed that PayPal’s business has lagged behind. Its active accounts remained unchanged at 439 million, while its active accounts rose by just 1%. Its growth has largely stalled after surging during the pandemic when most people embraced its platform.
PayPal’s earnings-per-share (EPS) is expected to come in at $1.31, slightly lower than the $1.34 it made last year. Recently, however, PayPal’s earnings per share have been better than expected, and this trend may continue this time.
Analysts also expect the upcoming guidance to show that its fourth-quarter revenue will be $8.99 billion, also up slightly from the $8.68 billion it made last year. If this is correct, its annual revenue will come in at $34.7 billion, up by just 3% from a year earlier.
PayPal’s Challenges are Continuing
PayPal’s business has slowed because of the rising competition from other fintech companies like Stripe and Block. Block’s Cash App has gained market share from Venmo, while its unbranded business competes with companies like Stripe and Affirm.
Most notably, its wallet business is facing substantial competition from Google Pay and Apple Pay. The company is also facing strong competition from stablecoins such as USDC and USDT.
PayPal is also a big player in the stablecoin industry through the PYUSD solution. Recently, however, there are signs that PYUSD’s growth has lost momentum. CoinMarketCap data shows that the coin’s valuation has slumped to $3 billion from $4.2 billion earlier this year. Its volume has also dropped in the past few months.
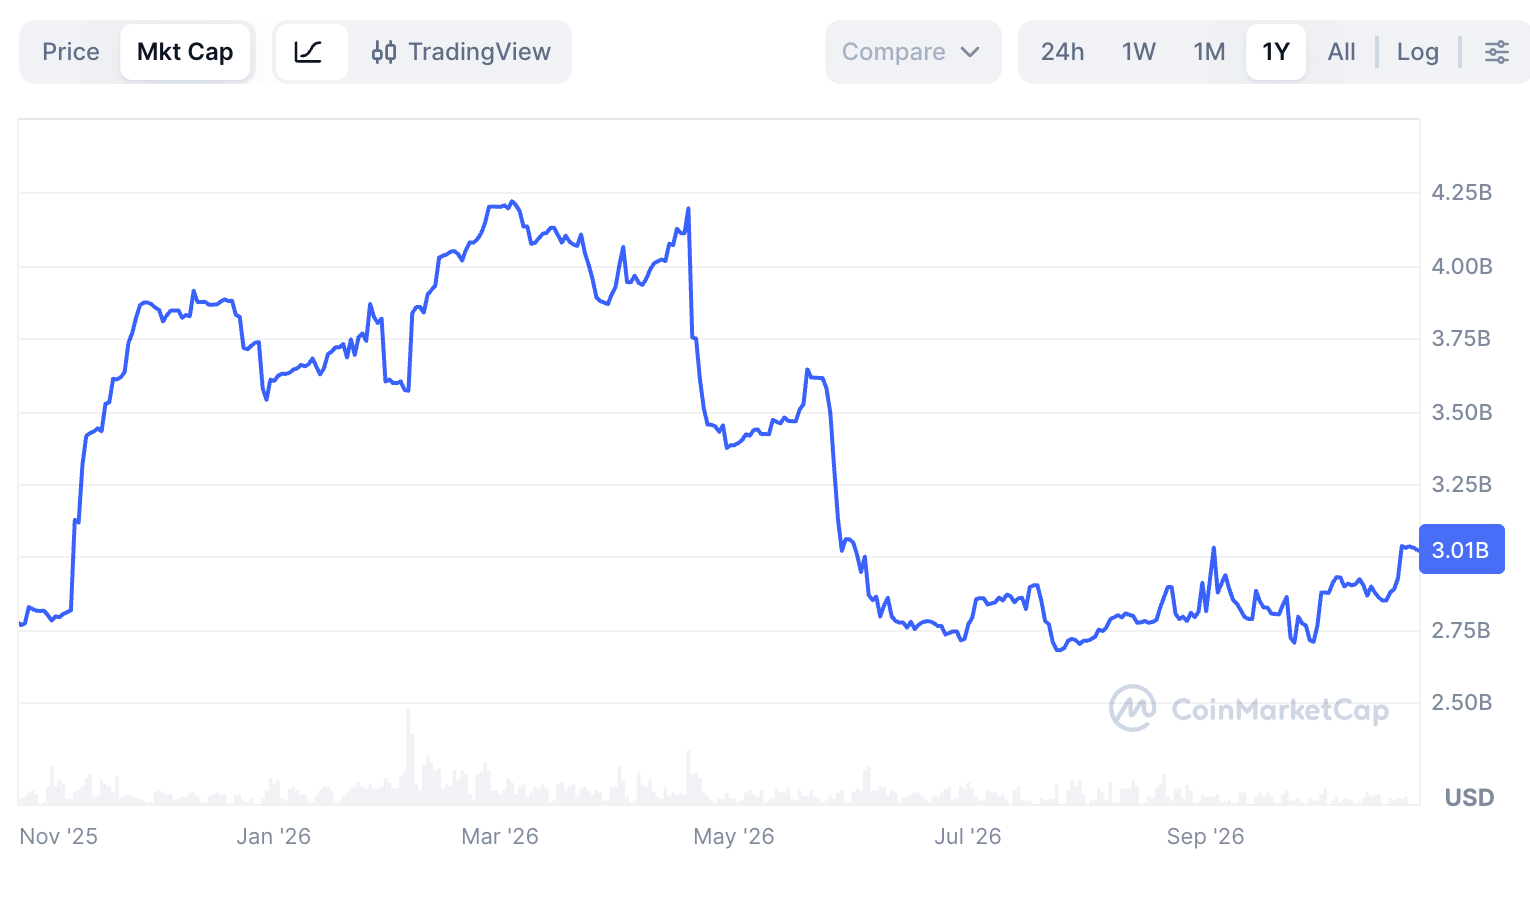
The current market cap suggests that PayPal is not generating substantial revenue from its stablecoin business. With the three-month Treasury bill yielding 4.3%, the stablecoin’s annual revenue is about $129 million, a tiny fraction of what PayPal makes.
Still, on the positive side, PayPal has become highly undervalued, with the forward price-to-earnings ratio being 10.5, slightly lower than the sector median of 11. This multiple is also much lower than the five-year average of 16.2.
As a result, the company could still become a takeover target, potentially by a private equity company.
PayPal Stock Price Technical Analysis
The daily chart shows that the PYPL stock has rebounded in the past few weeks, moving from a low of $50.80 in September to the current $57. It has flipped the Supertrend indicator from red to green, which is a bullish sign.
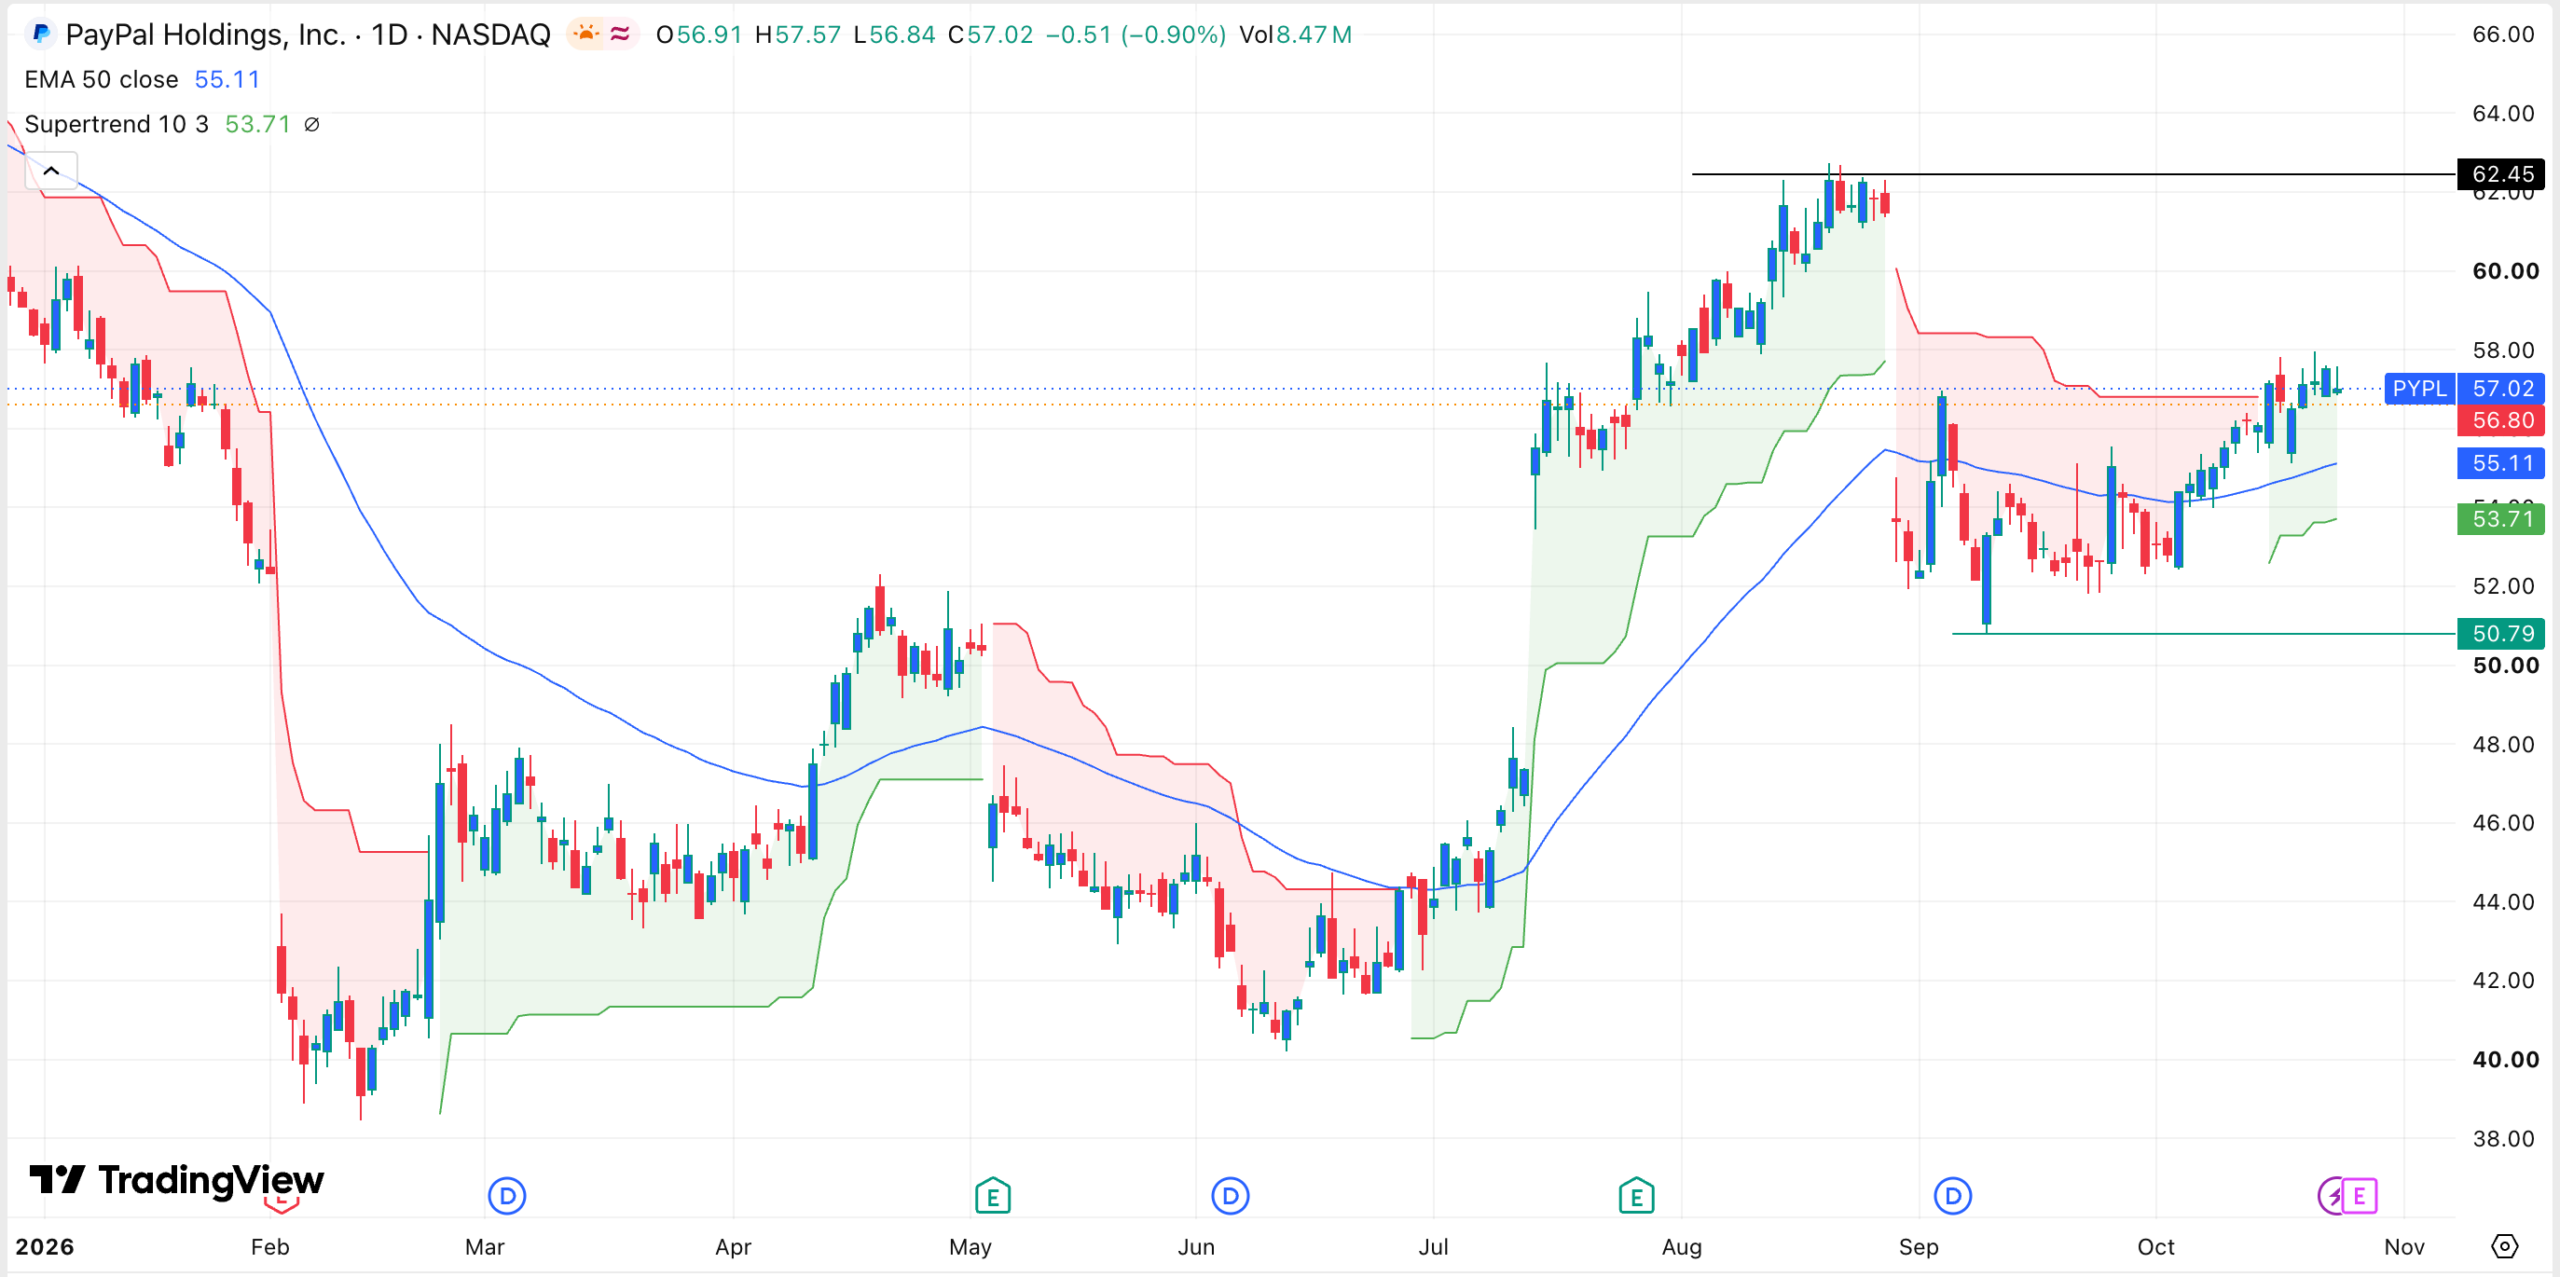
The stock has also jumped above the 50-day moving average, a sign that bulls have prevailed. Also, it seeks to fill the fair-value gap that emerged after Stripe abandoned the buyout. Therefore, the stock may continue rising as investors target the key resistance of $60. A move above that level will point to more gains towards $62.
This article is for informational purposes only and does not constitute financial advice. Stock investments carry risks, including price volatility and potential losses. Readers should conduct independent research before making investment decisions.