 Pudgy Penguins
 Bitcoin
 Initia
 Pearl
 Quantus
 Zcash
 Ethena
PayPal stock faced renewed selling pressure after the company reported slower third-quarter revenue growth on Oct. 27. Revenue increased just 2% to $8.58 billion, falling short of Wall Street expectations.
However, adjusted earnings beat estimates, and management raised its full-year profit outlook. PayPal also continued its share repurchase program amid concerns about its business recovery.
PayPal Revenue and Profitability Growth Has Stalled
PYPL stock dropped to $54.9 as investors reacted to its third-quarter earnings report, which showed that its business remained under pressure. Its results show that a company that once dominated the fintech industry has become a fallen angel. A fallen angel is a company that was once high-flying and one that has lost momentum.
The results showed that the company’s active accounts remained unchanged at 439 million, with Venmo being its only growing business. Its monthly active clients remained unchanged at 228 million, with the number of payment transactions rising by 7%.
PayPal’s payment volume stood at $487 billion, a 6% annual growth, the slowest pace since the fourth quarter of last year. As a result, its revenue rose by just 2% to $8.5 billion. This growth is much lower than that of other companies in the fintech industry, like Visa and Mastercard.
Most notably, the company expects that its revenue growth will remain under pressure in the final quarter of the year. It expects its fourth-quarter earnings per share to be $1.37, bringing its annual figure to $5.07.
These results show that the company’s core solutions are slowing. A good example of this is PayPal USD (PYUSD), its stablecoin. Data show that the stablecoin has a market capitalization of $3 billion from a record high of over $4.2 billion.
PayPal Boosts Buyback and Dividend
With its business slowing, PayPal’s management has embarked on financial engineering to boost its share price. It is doing that by boosting its share repurchase plan. In a statement, the company said that it returned $1.5 billion to shareholders through buybacks.
It has now repurchased shares worth $6 billion in the last 12 months, an important milestone for a company valued at over $50 billion. Over time, the company has reduced its outstanding shares from 1.16 billion in 2022 to 862 million. Share repurchases are usually bullish for a company because they boost its earnings per share.
The company also continued paying its dividends. It declared a $0.14 per-share dividend, and growth is likely to continue. Besides, the company has over $15.1 billion in cash and equivalents, which is also a substantial amount for a company of its size.
These numbers, together with its cheap valuation, explain why the company recently attracted a takeover bid from Stripe and Advent International. The bid fell apart after PayPal maintained that its business was worth more than that.
PayPal Stock Price Technical Analysis
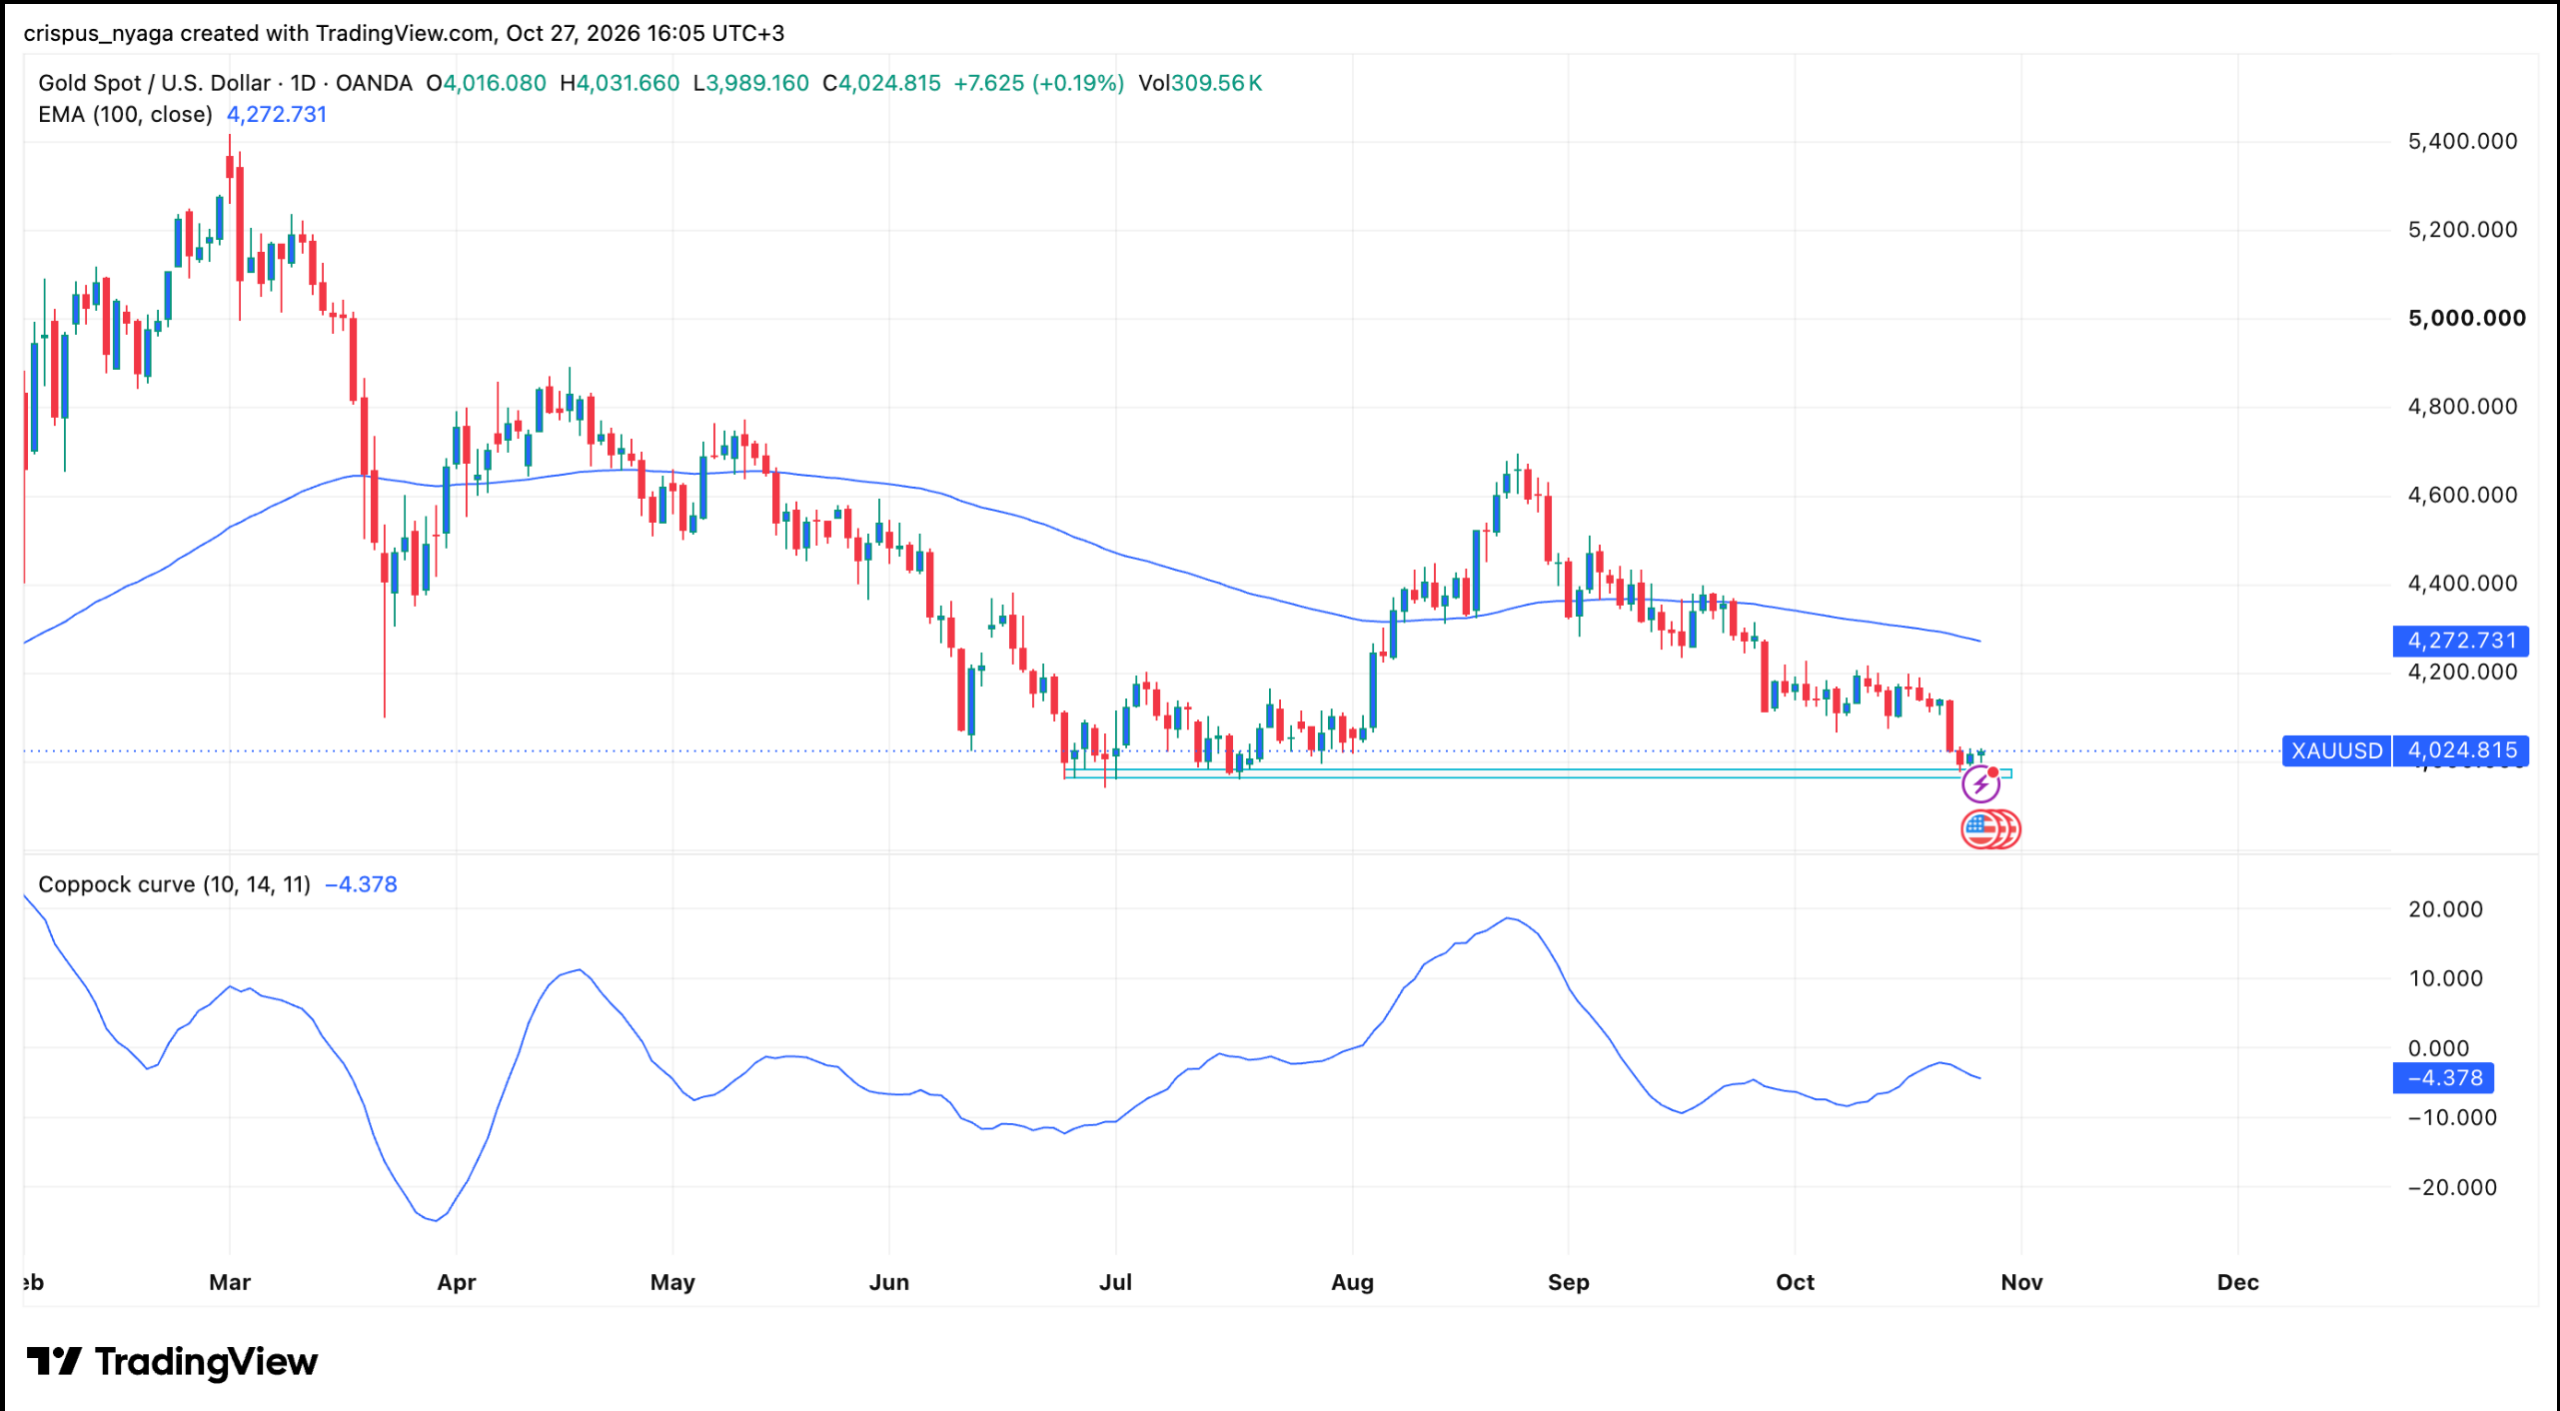
The daily chart shows that the PYPL stock bottomed at $38.52 earlier this year and then bounced back after Stripe and Advent revealed their takeover bid. It rebounded to a high of $62.60 in August and then retreated after the two ended their pursuit.
The PayPal stock remained in a narrow range, then dropped to $53.81 after earnings. This retreat has pushed it below the 50-day moving average, while the Cappock Curve has moved sideways.
Therefore, the stock will likely remain under pressure in the near term as sellers target the key support level of $50. A drop below $50 will signal further downside, potentially reaching the psychological level of $45.
This article provides information, not financial advice. Stock investments carry volatility and potential losses. Readers should conduct independent research before investing.