astronaut
 Pearl
 Zylo Ecosystem
 Bitcoin
 Bitway
 NEAR Protocol
 Zcash

Nvidia stock price has wavered since mid-last month as investors focus on its revenue growth and the emerging issues in its business like the China risks. A closer look at its technicals and client concentration risks signals that the NVDA stock may have peaked.
Nvidia Stock at Risk Amid Business Concentration Risks
Nvidia’s business has experienced relentless growth in the past few years, with its annual revenue jumping from $16 billion in 2021 to $165 billion in the trailing twelve months (TTM). Its net income has skyrocketed from $4.3 billion to $85 billion in the same period.
While the company may have more room to run, there are two risks that could affect its growth and stock performance. The first one is that the data center segment drove the recent growth because of the popularity of its GPUs.
The most recent quarterly results showed that its second-quarter results jumped to $46.7 billion, a 56% increase from the same period last year. A deeper dive revealed that $41 billion of this revenue was in its data center business.
Gaming and AI PC revenue rose by 49% to $4.3 billion, while professional visualization and automotive made $601 million and $586 million, respectively.
As such, these numbers mean that the company’s growth will be at risk if the AI sector experiences a downturn. A good example of this is the slowdown in Bitcoin mining and the metaverse a few years ago.
NVDA Has a Customer Concentration Risk
The other risk is that Nvidia’s revenue depends on just a handful of companies. In a recent statement, the company said that over 40% of its revenue came from 2 companies. Most analysts believe that Microsoft accounts for ~20% of its revenue. The other top clients are companies like Amazon, Google, and Meta Platforms.
All these companies have committed to continue spending billions of dollars on the data center industry. While this is good, there is a possibility that their spending will slow over time as they focus on realizing a return on their investments.
Such a move will affect Nvidia’s growth because it does not have the next big thing that will offset the scale of the AI segment. For example, while the recently launched robotics chips will fuel its growth, the automotive and robotics division is so small, generating just $586 million in revenues last quarter.
The customer concentration risk is also notable because the company has largely lost its Chinese business due to Donald Trump’s restrictions and the ongoing innovation by the likes of Alibaba and Cambricon.
Nvidia Stock Price Technical Analysis
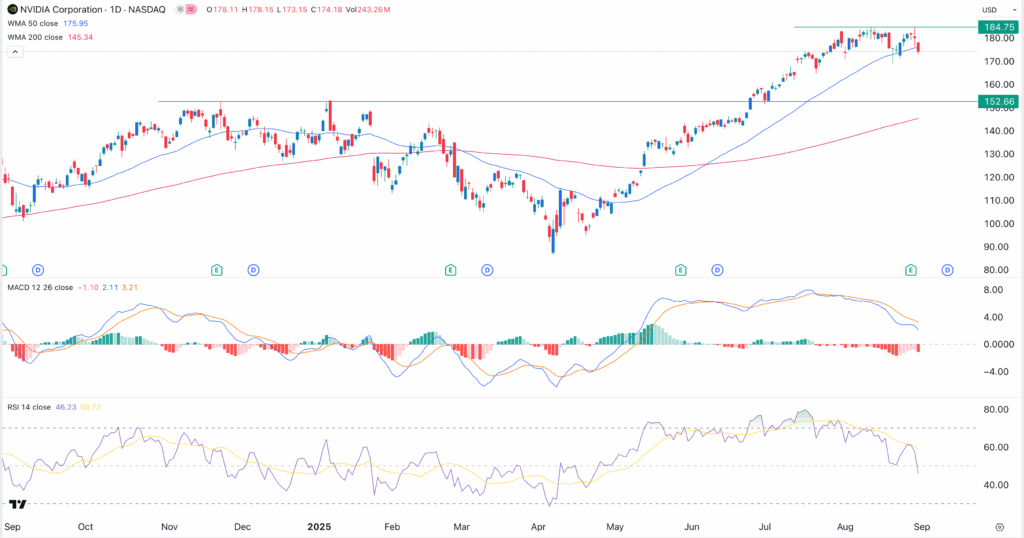
The daily chart timeframe shows that the NVDA stock price has moved sideways in the past few weeks. It topped at $184.75 in August and then pulled back to the current $174.18.
The stock has already moved below the 50-day Weighted Moving Average (WMA). At the same time, the two lines of the MACD indicator have formed a bearish crossover and are pointing downwards.
The Relative Strength Index (RSI) has continued to fall and moved downward to 46. If this happens the next key support to watch will be at $152, the highest swing in November last year and January. A move above the important resistance at $184 will invalidate the bearish view.
Summary
Nvidia stock price has moved sideways in the past few weeks as the growth trajectory eases. It has also formed a bearish divergence pattern, indicating further downside in the coming days. If this happens, the next level to watch will be at $152, a move that will erase billions of dollars in value.
Such a drop would be a divergence from what analysts expect. According to TipRanks, the average estimate among analysts is $212, with those at Wolfe Research, Bank of America, and Bernstein expecting it surge to $220.