Quack AI
 Lighter
 NeoSoul
 Pearl
 Quant
 Injective
 Pons

U.S. financial markets enter a packed week with inflation, economic growth and Federal Reserve policy expectations in focus. July PCE inflation, Q2 GDP revisions and Nvidia earnings all arrive Wednesday, creating one of the busiest sessions of the week.
Investors will then turn to Fed Chair Kevin Warsh’s Jackson Hole speech on Friday. Treasury auctions and escalating U.S.-Iran tensions could add further volatility across bond, equity and energy markets.
PCE Inflation Data Takes Centre Stage
The Federal Reserve’s preferred inflation measure, the July PCE price index, will be released on Wednesday. Economists expect core PCE inflation to increase by 0.2% month-on-month, keeping the annual rate above the central bank’s 2% target.
The report will provide fresh insight into price pressures before the September Federal Reserve meeting. Recent CPI and producer price data showed some moderation, reducing pressure on policymakers to make immediate changes to interest rates.
US markets will also receive the second estimate of second-quarter GDP and July durable goods orders on Wednesday.
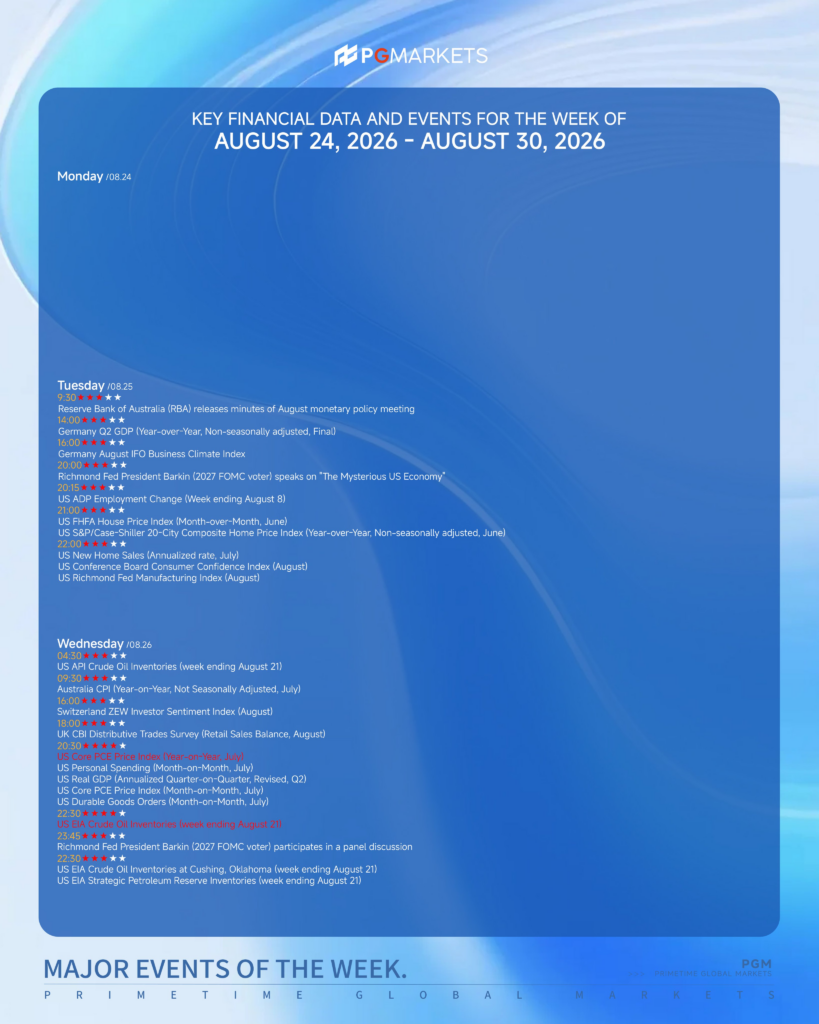
Consumer confidence data arrives on Tuesday, followed by weekly jobless claims on Thursday. The employment figures will provide additional insight into labour market conditions after recent reports showed signs of cooling.
Fed Chair Warsh Prepares for Jackson Hole Speech
Fed Chair Kevin Warsh will speak at the Jackson Hole Economic Symposium on Friday, August 28. The event brings together global central bankers and policymakers to discuss monetary policy and economic conditions.
Investors will monitor Warsh’s comments for details about the Federal Reserve’s approach to inflation, economic growth and interest rate decisions. The Fed has kept attention on inflation risks while reviewing incoming economic data.
The speech comes after changes in Treasury markets, with long-term yields rising in recent weeks. The U.S. Treasury Department responded by increasing long-end bond buyback operations for 10-year to 30-year securities.
Treasury auctions will also attract attention, with the government scheduled to sell $69 billion in two-year notes, $70 billion in five-year notes and $44 billion in seven-year notes.
Jobs Data and Growth Signals Remain Important
Employment indicators will remain a key focus for investors throughout the week. Weekly jobless claims on Thursday will show whether labour market conditions continue to soften.
The Federal Reserve has been monitoring employment alongside inflation when assessing interest rate policy. Recent labour data showed weaker hiring conditions, giving policymakers more time to evaluate economic trends.
Canada’s second-quarter GDP release will also arrive on Friday, adding another regional growth indicator for global markets. The data will show how the economy performed after facing pressure from trade uncertainty with the United States.
Meanwhile, consumer sentiment results from the University of Michigan will provide another view of household expectations. The report will arrive on Friday alongside Warsh’s Jackson Hole appearance.
US Markets Track Stocks, Commodities, and Energy Risks
Corporate earnings will remain part of the US market focus, with Nvidia scheduled to release quarterly results before U.S. markets open on August 27. The company’s results will provide updates on artificial intelligence demand and technology sector performance.
Energy markets will also attract attention after oil prices moved higher in recent weeks. Brent crude futures gained during the previous week, while traders monitored developments surrounding U.S. sanctions against Iran.
Treasury Secretary Scott Bessent is expected to announce details of new economic sanctions against Iran during the week. The announcement could influence energy markets and broader risk sentiment.